Prix des carburants : pourquoi les raffineries sont au cœur de la tempête
Plus que d'un problème pétrolier, la flambée des prix du carburant résulte de tensions sur les capacités mondiales de raffinage.
Get the latest as our experts share their insights on global energy policy.
Last week's summit between US President Trump and Chinese President Xi was the second meeting between the two leaders since the US and Israel attacked Iran.
Hear in-depth conversations with the world’s top energy and climate leaders from government, business, academia, and civil society.
Carbon credit markets have become one of the most hotly debated tools in the fight against climate change. Supporters call them essential to closing the gap between corporate...
Find out more about our upcoming and past events.
Apply to Register The Center on Global Energy Policy at Columbia University SIPA’s Women in Energy initiative invites Columbia University students to a roundtable discussion with Pam Brown,...
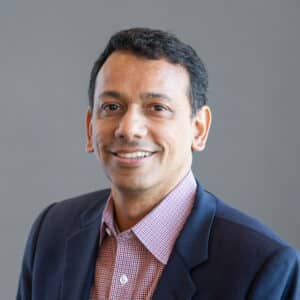
Senior Research Scholar
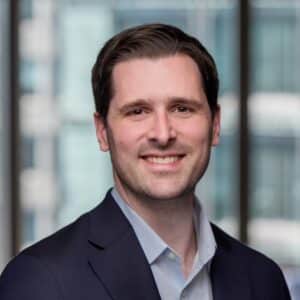
Director of Public Policy and Climate Finance Programs, Bloomberg
Ned Shell:
One of the missing pieces that I think countries are really stepping up on now is creating sovereign policies and regulations to guide and regulate the issuance and trading of carbon credits in their own markets. My expectation is a little bit more chaos for the next one or two years as everyone sort of figures out the right domestic regulatory regime that works for them.
Gautam Jain:
Without having proper infrastructure, essentially what that means is fully regulated exchanges or trading platforms. It’ll be difficult for this market to scale up.
Bill Loveless:
Carbon credit markets have become one of the most hotly debated tools in the fight against climate change. Supporters call them essential to closing the gap between corporate climate pledges and what companies can actually achieve on their own. Critics call them a shell game that lets polluters buy their way out of real action. But the debate is about more than just whether carbon credits can work. It’s about the integrity of the markets designed to trade them.
The promise of these markets is fairly straightforward. The complexity comes in determining whether the credits actually deliver the climate benefits they’re supposed to. New research from the Center on Global Energy Policy supported by Bloomberg Philanthropies examines the state of one type of carbon trading, project-based carbon credit markets. The study looks at how these markets are regulated and how they might be scaled.
This is Columbia Energy Exchange, a weekly podcast from the Center on Global Energy Policy at Columbia University. I’m Bill Loveless. Today on the show, Gautam Jain and Ned Shell. Gautam Jain is a senior research scholar here at the Center on Global Energy Policy. He focuses on the role of financial markets and carbon markets in the transition to net zero emissions, particularly in emerging countries. Gautam previously worked in the financial industry where he covered emerging markets as a portfolio manager and strategist for asset management firms and investment banks, including The Rohatyn Group, Barclays Capital, and Millennium Partners. Ned Shell is director of public policy and climate finance programs at Bloomberg. He is also a term member of the Council on Foreign Relations. Prior to Bloomberg, he served as consular to the undersecretary for domestic finance in the US Department of Treasury and held roles at Bain & Company and the World Bank.
We discussed what a carbon credit market actually is and how project-based carbon credit markets differ from voluntary and compliance markets. We got into the missed opportunity for US policy. The European Union’s moved to fold carbon removal credits into its emission trading system and what high integrity really means when it comes to these credits. And we looked at where the market is headed from Microsoft and Google’s diverging approaches to carbon removal to the road ahead for global rules under the Paris Agreements Article six. Here’s our conversation. Gautam Jain, Ned Shell, welcome to Columbia Energy Exchange.
Ned Shell (03:14):
Thanks Bill.
Gautam Jain (03:14):
Thank you Bill for having us.
Bill Loveless (03:16):
Carbon credit markets are a complex topic, one that’s confusing to many people. Gautim, can you explain in simple terms what carbon credit markets are and why they matter?
Gautam Jain (03:30):
Sure. Let me first start with what a carbon credit is. So carbon credit represents one metric ton of carbon dioxide equivalent removed from the atmosphere or reduced or avoided relative to a baseline. This enables assignment of a monetary value to a carbon turn, which is basically the value of this carbon credit. When carbon credits are generated from discrete identifiable projects, they’re called project-based carbon credit markets. The research that we did was on project-based carbon credit markets. These markets cover the generation, trading and settlement and retirement of these credits. In terms of why these markets are important or why do they matter, essentially project-based carbon credit markets provide incentives to companies, especially those that have net zero targets to finance decarbonization activities outside the scope of their business. So as a result, there is a flow of capital to finance decarbonization activities that would not have otherwise attracted investment.
(04:50):
Now, if you think in terms of what these projects are underlying these project-based carbon credits, they typically or many times are nature-based projects that are based in emerging economies typically. And when you think about who the buyers of these credits are, they’re typically companies in the hard-to-debate sectors, hyperscalers and so on that are looking to carbon credits to basically offset their residual emissions. And they’re based in developed countries, so essentially creates a flow of capital from developed to emerging economies.
(05:28):
Lastly, I’ll just make one more point. Some of these projects also provide co-benefits, co-benefits in terms of the preservation of land, forest, trees, water, and also biodiversity. And in the process, they support the local communities, economic development of these communities.
Bill Loveless (05:52):
So Ned, this latest research, which is funded by Bloomberg Philanthropies, as Gautam notes, looks at project-based carbon credit markets. How are these markets different from voluntary carbon markets?
Ned Shell (06:06):
So voluntary carbon markets are, it’s a bit of a misnomer because a voluntary carbon market pertains to the use of a carbon credit. A carbon credit itself is not inherently a voluntary credit or a compliance credit or some other sort of credit. How it’s used is where we talk about voluntary carbon markets. So if a company voluntarily purchases a carbon credit for any of the reasons Gautam just shared, then you could consider that as part of a voluntary scheme or voluntary trading. But I think folks often think a voluntary carbon market is a market from all the way from project generation through to purchase of credit. And actually it really is just, we’re just talking about the use of the credit. So if there’s a Venn diagram, project-based carbon credit markets would be the big circle and voluntary carbon markets would sort of be a nested circle because it just pertains to an application of carbon credits.
Bill Loveless (07:08):
Well, Gautam, how are they different from regulated carbon credit markets?
Gautam Jain (07:12):
Yeah, good question. So regulated carbon markets or compliance carbon markets in effect are doing the same thing in the sense they are also financing decarbonization, but they do it differently. Essentially, they control emissions by imposing a price on it, and this can be done through a carbon tax, which is a direct price on emission or an emission trading system, which is a cap and trade system typically. In these allowance-based emission trade systems, they work differently from PBCMs or project-based carbon credit markets because as I mentioned earlier, in the case of project-based carbon credit markets, they cover credits generated from mitigation, discrete mitigation projects. In the case of ETSs, the allowances are either allocated or auctioned by regulatory authority to regulated entities, and each of these allowance basically is a permit or permission to emit one ton of carbon.
Bill Loveless (08:20):
You’ve spent a considerable amount of time recently studying this type of market. Why is it, and Ned, you and your organization has supported this work, why are these markets important to the United States, to any country?
Ned Shell (08:38):
I can come in on the US angle. I mean, previously I worked at the Department of the Treasury in the Biden administration. We took a particular interest in these markets. The US has a big stake in these markets. On the demand side, many US companies are purchasers of carbon credits. We have compliance markets, state-based compliance markets in the US that have a role for carbon credits and meeting obligations like California. And on the supply side, we have producers of carbon credits. There’s actually a lot going on in the US, even though I think a lot of folks who are familiar with carbon credit markets think of it as more of an international phenomenon, especially something that’s quite active in emerging markets. There’s sort of an inherent interest that the US has both from a regulatory perspective and also an economic competitiveness perspective. Other countries are speeding ahead with regulations and policies to guide these markets, China, the European Union, and so there’s sort of a risk if we step back that our companies will be captured by other regulatory regimes that maybe we didn’t have an input into.
(09:54):
Also, and this was something the Department of Energy really keyed in on in the last administration here, we have quite a competitive advantage when it comes to some of the technology-based carbon removal and reduction technologies. And so there’s an ecosystem here that could really be supported and play a role on the global stage when it comes to generating these sorts of credits. But Gautam maybe I turn it to you for the international perspective.
Gautam Jain (10:20):
I think from the international side, if you think about emerging economies, many of them, as I mentioned earlier, they are generally in the context of international carbon markets, and especially when we think about the Paris Agreements Article six, these are countries that are typically sellers of credits. So from their angle, they would want to develop these markets because it allows them to be part of this international carbon market. And then on the other side of these seller countries are the buyer countries, some countries that are interested in meeting their NDCs and therefore they are willing to buy credits from other countries. These are countries including Norway, Switzerland, Singapore, Japan, Korea. There are many countries that are on the buyer side. So there are incentives for many countries to develop their carbon markets so that they’re part of this international or global carbon market.
Bill Loveless (11:18):
Well, I mean, just given what Ned was saying a minute ago about the United States and the significance of these kinds of markets to various players in this country, there’s not much happening in the way of policy. In fact, policy’s going in the other direction currently in the United States. Ned, how much of a risk is this to the players in the United States who might be interested in pursuing these markets?
Ned Shell (11:39):
I would say it’s more of a missed opportunity. I think the tailwinds behind these markets are strong enough that they don’t require US policy at this moment, but certainly it’s a missed opportunity to not really double down on policy that can support US companies that are making progress in developing both the supply and demand side of these markets. But I wouldn’t say it’s an existential risk. Secondly, there is innovation happening at the state level in the compliance markets that do permit a use of credits and certainly a very active non-governmental sector working on these things in the US.
Bill Loveless (12:18):
California among those players?
Ned Shell (12:21):
Yeah, exactly.
Gautam Jain (12:23):
If I could add to that, I think one of the other things that is a missed opportunity is right now we are in the process of setting global standards in some ways, and this report was going over regulations across G20 countries, except the US, because that’s part of another study. The point is that as these regulations develop, for the market to develop, there needs to be harmonization across these jurisdictions, and to the extent that US is missing from a picture and it’s not part of this standard setting, it’s kind of a missed opportunity for the US to play that role.
Bill Loveless (12:59):
Gautum, imagine I’m a company that cannot eliminate all of my emissions today. How does a project-based carbon credit actually work from beginning to end? Can you give me an example?
Gautam Jain (13:11):
Sure. So if you think about any company, you look at their emissions across their value chains, scope one, two, and three emissions. So the typical idea is that you would eliminate as much of these scope one, two, and three emissions as possible as is economically possible. And then there’s a certain threshold beyond which reduction of emission through technological advancement or any other approaches becomes very expensive, basically prohibitively expensive. So you have a choice, you can either just let it be or you can then invest in some of these carbon credits to meet your target, net zero target and essentially eliminate your residual emissions. So this is the place where carbon credits can play a role. Of course, this is where regulations come into play in the sense that they need to define, and we can go into that a little bit, from the demand side, how companies can use and disclose very clearly the use of these credits.
(14:13):
This is one place, and this is what we point out in our research, is where regulations are still lagging in general around the world. There are some countries that have made more advances, but in general, they are still lagging.
Bill Loveless (14:28):
So in a sense, the promise of these markets is fairly straightforward. The complexity comes in determining whether the credits actually deliver the climate benefits they’re supposed to. Is that a fair way to put it?
Gautam Jain (14:40):
I would say that’s one side of it. So that is the credit generation side, but that’s an extremely important point. So the credit generation side, and maybe I’ll take a step back, and Ned is very familiar with that. In fact, that was his idea to think about regulations in this way, which is dividing them into supply side regulations, demand side regulations, and then market side regulations. The supply side regulations basically ensure that the credit generated meets this quality thresholds, the transparency in how it’s generated, they fall under specified MRV regimes and so on. So those focus primarily on the environmental integrity of credit from the generation side. The demand side focuses on the use and disclosure of credit by buyers. And this is the place, as I was mentioning earlier, is where more needs to be done. And this is where it’s important that that part also gets addressed, not just the generation side.
(15:47):
And finally, you need the market side regulations because without having proper infrastructure, essentially what that means is fully regulated exchanges or trading platforms. It’ll be difficult for this market to scale up. So you need all three to develop simultaneously for this market to scale up and generally to build market trust so investors can have confidence that there’s recourse, they have confidence in the environmental integrity of credits, and that’s the condition that’s needed for this market to grow.
Bill Loveless (16:22):
Gautam, what are some of the solutions that your research offers?
Gautam Jain (16:27):
So let me maybe compare PCCMs to other approaches that we have faced over the centuries. So they’re good examples. And in that context, explain why regulations are important for this market to scale up. As Ned was mentioning earlier, when you think about voluntary carbon market, it’s only on the use side. You have to think a little bit more broadly. And when you think broadly, if I can cite examples of other markets and how the lessons or what the lessons we can learn from them, that’ll be useful. So in that context, let’s talk about the US stock market, for example. So the US stock market before the passage of the Security Exchange Act in 1934 was a self-regulated market. So what that means is there were exchanges like New York Stock Exchange that worked like private clubs. They would set their own standards, they would monitor and police their members.
(17:28):
But what happened was eventually the market devolved into malpractice in terms of insider trading, market manipulation, explicit fraud, which culminated as we know in the market crash of 1929. So then the Security Exchange Act passed, and since then, obviously, you can see the transformation of this market. It’s the largest and more liquid capital market in the world. The second example I would like to give is that of commodity markets. Similar to the US equity market, going back to the 1850s, Chicago Board of Trade basically came up with trading practices, forward contract specifications and so on for trading commodities. It was decades later that actual federal oversight came into play. This was with the passage of the Grain Futures Act in 1922, followed by the Commodity Exchange Act in 1936. Since then, again, this is a market that has expanded and become very liquid. So lessons that you take from these two, which is pertinent to the question you asked is how does this market can grow, first lesson is that you need regulations which provide enforceable safeguards to build market trust for any market to scale up.
(18:53):
That’s lesson number one. Lesson number two, you don’t need to start the regulations from scratch. There are market practices that are already in place. So these regulations can basically codify and essentially codify these standards that are already common market practice and just make sure that they’re enforced and essentially through a regulatory body that they can put on top. So these are essential conditions for the market to thrive and grow.
Bill Loveless (19:28):
When you think of carbon markets and trading systems, of course I think of the European Union, and just last week, the European Commission announced it will be integrating carbon removal credits into its emission trading system. Gautam, you said this is a big step forward in line with what you’ve written in the report. I’d like to hear what you and what Ned thinks of that move by the European Commission.
Gautam Jain (19:53):
Sure, let me start. So this is a pretty important move. One of the findings from our report is that more and more jurisdictions are allowing or permitting the use of carbon credits in compliance markets. And so the line between the compliance and voluntary market is blurring, which was what Ned was referring to earlier when we talked about PCCMs versus voluntary carbon market. So what EU ETS announced was integration of carbon removal credits into the ETS. This is a pretty big step forward, but it’s not exactly the same as the example or what are finding showing that more and more jurisdictions are allowing for carbon credits to be used in compliance market. It’s slightly different in the sense that the way they’re going to do this is they will issue more allowances, so 250 million tons of allowances over 10 years, and then they will use the proceeds from the allowances to buy carbon removal credits.
(21:04):
So again, they’re financing this very important decarbonization activity, but it’s not coming through a regulated channel, which would be a regulated entity having the option of using either the allowance or the carbon credit for the emissions they’re making. That’s not quite the same, but has the same end result. Ned, I don’t know if you have anything more to add there.
Ned Shell (21:27):
No, I would just add, it sort of speaks to the evolution of these markets that the EU has done this because several years ago, for example, when I was in the US government, the idea that the EU would go ahead with including carbon removal credits in its compliance scheme was pretty… No one though that would happen. And so I think it just speaks to the global momentum around finding ways to make these markets work, including them in compliance schemes and scaling them when you have a jurisdiction like the EU making moves on it.
Bill Loveless (22:05):
Yeah, just want to underscore the term carbon removal credits. My understanding is that these involve things like direct air capture and other technologies that physically remove carbon dioxide from the atmosphere, correct? And it’s different from traditional project-based carbon credits there. As I understand it, you’re talking forest conservation or methane capture, these sorts of things.
Ned Shell (22:30):
You’re definitely speaking to a wider dynamic in the carbon credit community, which is the difference in integrity and environmental integrity of removal credits versus what others would call avoidance or reduction credits. And the EU has clearly signposted that, or I would say my perception is that by doing this, it’s signposting that removal credits are sort of “better,” but you’ll get a lot of different opinions about that question depending on who you speak to.
Gautam Jain (23:00):
And if I could add to that, so the idea behind this is the EU is going to use its own regulation, CRCF, which stands for carbon removal and carbon farming regulation that they passed a little over a year ago, and they have been coming up with methodologies. So the idea is that they want to use that to identify the projects that can qualify to be bought. But you are right, and as Ned mentioned, removal versus reduction credits, there’s a debate ongoing, but the market generally feels more confident on removal side. But removal, by the way, can happen both with technology and nature-based projects. So if it’s an air forestation or reforestation project, that’s also a removal project. It’s just nature-based versus technology-based, which is DAC with CCS or bioenergy with CCS and so on. But you’re right, in the case of EU CRCF, it is essentially, at this point, they’re talking about the technology-based removals.
Bill Loveless (24:04):
And you’ve talked about this term, high integrity carbon markets, but I want to make sure I understand what that means, high integrity carbon markets. What do you mean by high integrity?
Gautam Jain (24:14):
So a high integrity credit is one that generates real, additional, quantifiable, verifiable, permanent, and unique reductions in greenhouse gas emissions. Let me talk about each terms here. It has to be real, quantifiable, and independently verifiable. So somebody can very clearly go and see through an independently verified company that this emission actually happened. Then it needs to be additional. Additional means that the project would not have been commissioned without the money raised through this carbon credit, would not have been able to come into existence without that. So it needs to be additional. It needs to be permanent because carbon dioxide can stay in the atmosphere for thousands of years. You need to ensure that whatever carbon is captured, it stays there for a long period of time. Again, how do you measure that? And whether it’s 30 year, 100 years, what do you do in case of any sort of unforeseen events?
(25:28):
For example, nature-based projects, if there’s a wildfire, if there’s insect infestation, there are many things that can happen, plus human activity like they’re cutting the forest. So things like that, what are the mechanism for reversal? How do they address that? And unique in the sense that it should not be double counted in the sense that let’s say one country is where the project is, it should not be the case that if the credits for that project is sold to a company or a government in another country that’s counted for both their NDCs, for example. So it needs to meet all these conditions for it to be a high integrity credit.
Ned Shell (26:15):
And I think one reason that at least I think regulation and policy is needed is because one of the reasons these markets have not scaled is because there are really serious remaining questions around the level of quality of these credits in the market and just left to their own devices, you might have fraud, you might have overestimation. There are plenty of news articles out there about examples of this in the past. And so one thing that regulation and policy can help with is really laying out clear consequences for bad actors, laying out much more trusted mechanisms for verifying reductions and removals and putting that architecture around a market that really just needs, I think, more heft and trust in how it operates. I think there are definitely tailwinds on this. I mean, the Integrity Council for Voluntary Carbon Markets is very well known body that approves methodologies quite trusted.
(27:23):
There’s progress on Article 6.4. So I think globally we just want to see more convergence around international best practice on these supply side standards.
Bill Loveless (27:31):
And Gautam there are models out there. I read recently an item that you wrote with our colleague Luisa Palacios at the Center related to your research having to do with international mechanisms that have cropped up in recent years, such as in aviation where you write there is a well-defined program for purchasing carbon credits. Can we look to actions such as that as perhaps providing models for how these markets should form effectively?
Gautam Jain (28:05):
Yeah, I think you’re talking about CORSIA specifically, which is carbon offsetting and reduction scheme for international aviation. This has been quite a successful effort in the sense that they have defined a threshold for airlines, so they need to essentially keep their emissions to 85% of the level in 2019. So what that means is to make sure that the emissions are at that level, any excess emission need to be met or offset by using carbon credits. So what CORSIA has managed to do is to generate this demand for high integrity credits because they are very specific on the rules on what kind of credits are allowed. So they have helped improve or increase integrity of the market. Generally, the credits that are CORSIA eligible trade at a premium to other credits. So that is one effort. The other one is obviously article six, Paris Agreements in article six.
(29:14):
This has been obviously a long drawn effort going on for the past 10 years, but it seems to be getting to a point where it should become operational soon. There are already some deals that have been closed. More than a hundred bilateral agreements have been signed between countries. The two important articles, 6.2 and 6.4, but in article six, 6.2 refers to bilateral trades. This is where I was talking about the bilateral agreements now. 6.4 refers to creating a more global carbon market. This is still in the works in the sense that defining the methodologies to make sure the credits that trade are high integrity. So this is getting to a point where should start trading and it’s expected to be fully operational within a year or so. Both these initiatives have the potential, first A, to create demand for high integrity credits, and B, to, as a result of that, scale up, help scale up the market as a result of the demand, and improve or increase credit integrity in the process.
Bill Loveless (30:25):
Yeah. As I understand it, and Ned, correct me if I’m wrong here, Article six of the Paris Agreement is an international rule book for carbon markets and cooperative climate action, and one that allows countries to voluntarily collaborate to meet their emissions targets or their national determined contributions, their NDCs, through carbon trading and non-market approaches while strictly preventing double counting. How do you think countries are preparing to connect with this?
Ned Shell (30:56):
I think there’s a lot of incredible progress being made on article six, but one of the missing pieces that I think countries are really stepping up on now is creating sovereign policies and regulations to guide and regulate the issuance and trading of carbon credits in their own markets. They’re not just going to rely on a UN system for these things. You’re seeing individual countries create their own registries, their own supply side standards, their own issuance guidance. And I think that’s really important because countries will have their own need to manifest their own interest in what they get out of these markets. And so applying that layer on top of the UN system allows them to get the most out of carbon credit trading given whatever their domestic industries are that generate credits or whatever the interests are of their domestic companies that are purchasing these credits.
(31:58):
Gautam’s research is all about how those efforts are in some ways converging and in other ways diverging. And then what I think you’ll see over the coming years is this sort of widening of the aperture of how countries are approaching these markets from a regulatory and policy perspective, and then a narrowing of it as we see what works and doesn’t and how that can dock in to article six and be interoperable with the international system for trading. So my expectation is a little bit more chaos for the next one or two years as everyone sort of figures out the right domestic regulatory regime that works for them, but they also need to make it interoperable with the systems that other countries have and with the UN system. And I think we’ll get there, but I think we’re sort of in that innovation stage right now…
Bill Loveless (32:52):
Yeah
Ned Shell (32:52):
The finalization stage.
Bill Loveless (32:53):
Still much work to be done as is often the case when it comes to Paris Agreement protocols and mechanisms, but you see that some progress is being made. Microsoft and Google have made news on carbon recently, but for somewhat different reasons. The biggest story came from Microsoft, which has been by far the world’s largest corporate buyer of carbon removal credits. In April, reports emerged that Microsoft had paused signing new contracts for carbon removal credits while it reassessed its procurement strategy. And meanwhile, Google continues to make major commitments to high quality carbon removal. These two companies are often held up as leaders in corporate climate action, yet it seems they’re taking somewhat different approaches to carbon credits today. Gautam, what do these decisions tell us about where carbon markets are headed today?
Gautam Jain (33:49):
The reporting that you mentioned for Microsoft not withstanding, the hyperscalers are a big source of demand for carbon credits. The reason is obviously they are building and investing in data centers. As a result, the emission profile is increasing basically. So this is making their, and Google said it as much themselves by the way, that this is making their ability to meet their 2030 net zero target more complex and challenging than ever. Having said that, they reaffirmed their target. So what that means is that means to meet their target, they would, if anything, need to buy more credits in addition to doing other investments for renewables and others that they may do directly. So that is an important point to make. In the case of Microsoft also, even though this was sort of reported, Microsoft did not confirm or deny the report. And since this report came out, they have gone ahead and closed at least one deal for 650,000 credits.
(35:03):
So clearly they’re not exiting the market. Again, in the sustainability report that also came out this month, it became clear that their emissions went up by 25% in 2025 relative to 2024, again, because of this build out of data centers. So I don’t necessarily think it is retrenching in any ways. If anything, you see the potential to grow. Of course, we have to see how serious the companies are about meeting their targets, and I would assume they are, in which case you would think that if anything, it adds to the demand for credits. Microsoft is important because to the carbon removal market, it was essentially the offtaker of 90%, which is roughly around 45 million tons last year. So it’s not insignificant if they do step back, but it seems like they’re still in the market, maybe not to the same extent they were. It could be a temporary adjustment that they need to make.
Ned Shell (36:08):
I also would add, just taking a step back, this has happened before, a tech company, there’s some question about whether they’re going to keep purchasing credits and then the carbon credit market freaks out a little bit. I think it just underscores the volatility of a market of today’s voluntary market where there aren’t that many large buyers. And in fact, is this a real market if one company has 90% of the purchase share? I mean, I can’t think of many markets like that. So to me, it just emphasizes the need to get more buyers, more participants into this market. And to do that, they need to have trust and confidence in what they’re buying in the system for trading and selling credits. And to do that, you need policy and regulation, which is really what all of this work is about that Gautam and CGEP have done.
Gautam Jain (36:58):
And if I can add one more point to that, we just spoke about UETS. EUETS will be buying carbon removal credits. So in effect, and the number is 250 million tons worth over 10 years, so roughly 25 million tons. So roughly around half of what Microsoft, more than half of what Microsoft was buying, they will make up to the extent they follow up, assuming that’s the math we do. The amount that they buy may be different because it’s 250 million tons of allowances they will issue. But you get the idea that there are other demand sources, as Ned was saying, come into picture. This is where other sources like compliance markets becoming more relevant comes into picture in the sense that as more compliance markets allow for carbon credits, the relevance on the voluntary side of independence on a few buyers becomes less important. So to give you some insight into that, if you go back a couple of years of the credits retired, less than 10% were those that were surrendered to compliance markets.
(38:15):
Last year, that number was between 20 and 25%. So compliance market is becoming an important source of demand. The other important sources, CORSIA and article six that we just spoke about. So the different diversified demand sources that are coming and exactly as Ned was saying, instead of being dependent on one or two companies, where we are headed is a place of more demand sources that removes this or reduces the volatility, which comes when there’s a concentration in a couple buyers.
Bill Loveless (38:50):
So Gautam, suppose you were a CEO of a company with a net zero commitment. Based on your research, would you buy project-based carbon credits today? And if so, what would you insist on before purchasing them?
Gautam Jain (39:06):
Yeah, good question. So for me, one of the things that is very clear in our research, by the way here, I need to give credit to my other co-authors in my research, which was my colleagues, Preetha Jenarthan, Victoria Prado and Shubham Deshmukh, along with obviously you mentioned Luisa Palacio with Josh Zoffer, and Ned obviously has been super critical to this project. But going now to the research, one of the thing that becomes clear, and I was sort of mentioning this earlier, about having clear regulations on the supply side, demand side and market side. So if you’re a company in a country where you have pretty strong regulations in place in all these three categories, so you feel confident in terms of participating in this market because if demand side rules are clearly in place, that means they have defined how a company can use these credits, what they need to do, what kind of verifications they need to do to make sure these are high integrity credit, what kind of disclosures they need to make, then as a company, you would feel confident that you’re not taking legal risk, you’re not facing reputational risk, you’re not facing or getting accused of greenwashing and things like that.
(40:29):
So you want to make sure that the regulations are in place and they’re very clearly defined so that when you do actually go and buy these credits, you are following the law. And as long as you’re following the law, you feel more comfortable. So that’s kind of what I would as a company would like to see. Supply side and market side are also important because without those, the market won’t scale up. So if as a CEO of a company, you want to be part of a market that’s liquid, for the market to be liquid and it needs to be large. And for those who need supply side and market side regulations as well. So you basically need all these elements to be present in the country that you’re buying this. Of course, ideally you would want this to be global in the sense that you want this to be true in countries around the world because if you buy credit and let’s say instead of offsetting your emissions, you decide to sell those credit back to the market.
(41:30):
So then you need a global market to be in place. So to the extent those credits are fungible in other countries will make your life so much easier. So ideally you want this landscape to develop, the regulatory landscape to develop across countries around the world.
Ned Shell (41:47):
I’d just quickly add, I would say there’s some consensus among many corporate leaders that the purchase of carbon credits is supplements what they’re doing within their own supply chain and within their own company operations. Several companies are criticized for not looking at their own actual operations and reducing emissions where they could there and only relying on credits. And so I think at least on the voluntary market side, it’s really when you pair both of those activities that you’re sort of achieving what you’ve set up to do.
Gautam Jain (42:20):
And this is a very important point from Ned in the sense that the regulations can define a mitigation hierarchy. And this refers to the question you asked earlier, Bill. So if the regulation very clearly lays out that you need to, up to this point, reduce your own scope one, two, and three emissions before you buy credits, it’ll make it so much easier for companies to make decision that we are at this point where it is okay for us to buy these credits. So you need to be very clear and regulations can make it very clear for you.
Bill Loveless (42:52):
Ned, looking at the big picture, where do you think more work is needed?
Ned Shell (42:56):
I think, to be honest, on all three parameters that Gautam mentioned, so we have supply side regulation, market regulation and policy and demand. I mean, the good news is there’s a lot happening on all of those. So I mentioned ICBCM and article six for supply side. On the market side, and this is one that I think a lot of folks don’t pay as much attention to, there needs to be more sort of building of the nitty-gritty plumbing that undergirds any market of tradable assets. And so in the case of carbon credit markets, and at Bloomberg, we support an effort called the Common Carbon Credit Data Model, which was initiated last year at the request of the G20. This is a data model that can undergird the issuance and trading of carbon credits across countries so that no matter where you’re getting a credit, it has the same data labels and descriptors as any other credit.
(43:56):
And you just can’t have a tradable market if a credit coming from Indonesia has different attributes or is described differently or its impact is described differently than a credit coming from South Africa. And so Indonesia’s piloting this effort right now, and I expect it’ll become quite widespread over the coming years. And then second,
Bill Loveless (45:24):
Well, before you go, let me ask each of you this question. You can start with Gautam. Five years from now, will project-based carbon credits be larger, smaller, or fundamentally different?
Gautam Jain (45:37):
I think it’d be larger and different in the sense that some of the things we talked about will be in place. So I see a scenario where we have regulations, which we already, in our research, we see kind of evolving in many countries and coming about. So what I see is a move towards a more state anchored, integrity-driven, interoperable architecture that can come about in a way that you stop thinking about carbon credits simply as voluntary offsetting instruments and start thinking of them as part of a broader climate governance system in a country. So you can see more and more integration of this market into the compliance market. You will probably see stronger integrity rules coming from regulations. You can probably see better demand side rules coming into place, which would make it easier for companies to deal with the legal risks. You’ll also see registries.
(46:48):
Registries are pretty important in this whole framework and registries becoming more critical to the infrastructure because governments realize that these are not just record keeping tools, but they can be regulatory instruments as well because they can help control eligibility, they can help prevent double counting, they can help enforce MRV and disclosure requirements and so on. And finally, I see as the market grows, which I do see it happening, more financial oversight coming into play.
Bill Loveless (47:29):
Ned, last word.
Ned Shell (47:31):
Honestly, I agree. I mean, I think it will be larger. I think there was a question a few years ago of whether these markets had a future and despite all the challenges and high profile failures of certain projects, they persist. And so I think there is a lot of energy from policymakers and market participants to make these succeed. And I think there’s a will, there’s a way. And I think Gautam’s research is really going to facilitate that because it’s going to allow governments to see what others are doing, what’s working, what’s not working, collaborate together, figure it out and create a global system that has higher integrity, higher tradability, and has integrated carbon credits into more mandatory and compliance systems.
Bill Loveless (48:18):
Well, it’s a complicated topic, but one where so much seems to be going on, often under the radar, at least in the eye of many of us who are not involved in these deliberations around the world. But it’s an important one and you guys have discussed it so clearly and so well for us. Gautam, Ned, thanks for joining us on Columbia Energy Exchange.
Gautam Jain (48:41):
Thank you
Bill Loveless (48:41):
For having us.
Ned Shell (48:42):
Thank you, Bill.
Bill Loveless (48:48):
That’s it for this week’s episode of Columbia Energy Exchange. Thank you again, Gautam Jain, Ned Shell, and thank you for listening. The show is brought to you by the Center on Global Energy Policy at the Columbia University School of International and Public Affairs. The show is hosted by Jason Bordoff and me, Bill Loveless. Mary Catherine O’Connor produced the show, Greg Vilfranc engineered it. Additional support from Caroline Pitman and Kyu Lee. For more information about the show or the Center on Global Energy Policy, visit us online at energypolicy.columbia.edu or follow us on social media at Columbia U Energy. If you like this episode, leave us a rating on Apple, Spotify, or wherever you get your podcasts. You can also share it with a friend or colleague to help us reach more listeners. Either way, we appreciate your support. Thanks again for listening. We’ll see you next week.
Carbon credit markets have become one of the most hotly debated tools in the fight against climate change. Supporters call them essential to closing the gap between corporate climate pledges and what companies can actually achieve on their own. Critics call them a shell game that lets polluters buy their way out of real action.
But the debate is about more than just whether carbon credits can work; it’s about the integrity of the markets designed to trade them. The promise of these markets is fairly straightforward. The complexity comes in determining whether the credits actually deliver the climate benefits they’re supposed to.
New research from the Center on Global Energy Policy, supported by Bloomberg Philanthropies, examines the state of one type of carbon trading: project-based carbon credit markets. The study looks at how these markets are regulated and how they might be scaled.
Today on the show, Bill Loveless speaks with Gautam Jain and Ned Shell about the state of project-based carbon credit markets, where it’s headed, and what they’re watching closely on the road to global rules under the Paris Agreement’s Article 6.
Gautam Jain is a senior research scholar here at the Center on Global Energy Policy. He focuses on the role of financial markets and carbon markets in the transition to net-zero emissions—particularly in emerging countries. Gautam previously worked in the financial industry where he covered emerging markets as a portfolio manager and strategist for asset management firms and investment banks, including The Rohatyn Group, Barclays Capital, and Millennium Partners.
Ned Shell is director of public policy and climate finance programs at Bloomberg. He is also a term member of the Council on Foreign Relations. Prior to Bloomberg, he served as counselor to the under secretary for domestic finance in the U.S. Department of Treasury and held roles at Bain & Company and the World Bank.
Global gas markets, especially in Europe, are approaching winter under serious pressure. With storage inventories lagging behind historical averages and shipping disruptions from the Middle East threatening key...
Seven months into the largest oil supply disruption in history, there's still no resolution in sight. This week, on the sidelines of the UN General Assembly, US and Iranian officials held their first indirect talks since the Memorandum of Understanding collapsed in July—but neither side appears ready for concessions.
This week, Chinese President Xi Jinping travels to Washington for a state visit with President Trump, their second face-to-face meeting this year. Energy is likely to be high...
More than six months into the war with Iran, the Strait of Hormuz crisis continues to cause turmoil in the Gulf region and global energy markets with no...
Project-based carbon credit markets (PCCMs) facilitate the generation, trading, and retirement of carbon credits from projects that remove, reduce, or avoid greenhouse gas emissions.
The World Bank is revisiting one of its most entrenched positions, publicly questioning its long-standing emphasis on market-led approaches in economic policy.